
CGFM Exam Questions PDF
| Questions and Answers | 1103 (Complete Set) |
| File Format | |
| Latest Update | November 19, 2026 |
| Files Delivery | Instant (5 to 10 min.) |
| Compatibility | All Desktop and Mobile Devices |
| Delivery Method | Download Account |
The Certified Government Financial Manager credential from AGA recognizes financial professionals in government. It requires passing three exams covering the governmental environment, accounting and reporting, and financial management and control.
Financial professionals use Certified Government Financial Manager to demonstrate knowledge that employers, regulators and clients can trust. The credential covers both technical content and the ethical and regulatory standards that govern financial work.
The Certified Government Financial Manager exam blends concepts, calculations and applied scenarios. Candidates who practice calculations until they are routine and then focus on interpreting results usually find the exam much more manageable.
Here is how the main areas break down. Governmental Environment covers structure, budgeting and ethics. Within Accounting, Financial Reporting and Budgeting, candidates should be comfortable with GASB and FASAB. Financial Management and Control focuses on internal control and audit.
Preparing for the CGFM exam requires not only understanding the exam topics but also practicing with exam style questions. Our Certified Government Financial Manager exam questions in practice tests help candidates review key concepts and familiarize themselves with the format and difficulty of exam.
At Killexams.com, our team works to maintain up-to-date practice content for exam preparation. We continuously review and refine our question sets and explanations to cover the latest relevant syllabus areas and help learners strengthen their understanding of core topics before facing the official exam. These Practice tests allow you to identify areas where you need improvement by measuring your readiness, and provide you exam questions to polish those areas.
CGFM Exam Questions Preview
Each CGFM exam has 115 multiple choice questions over about three hours.
A structured plan keeps CGFM preparation on track. Allow roughly 4 weeks, giving each major area its own block: begin with Governmental Environment, continue with Accounting, Financial Reporting and Budgeting; and Financial Management and Control. Keep a one page summary for each area with key terms, steps and examples, and review these summaries every few days. Leave the final week for full timed practice tests and targeted review of weak areas.
For CGFM, practice calculations with your approved calculator until they are fast and accurate, and keep a formula sheet that you review daily. Then focus on interpretation, since many questions ask what a result means for a decision.
Study regulations and standards for CGFM using summary tables that show purpose, scope, key thresholds and timing. Scenario questions often hinge on these details.
| Detail | Information |
|---|---|
| Exams | 3 |
| Questions | 115 each |
| Provider | AGA |
To help you evaluate our material, you may download free sample pdf with example questions and answers that we provide. This sample allows you to review content and approach before deciding on Premium materials..
The Certified Government Financial Manager practice test files contains 1103 Questions, are compatible with multiple devices, including Windows, macOS, iOS, and Android, and can be used for both online and offline study. The PDF format is printable, making it easy to study during travel or when away from a computer. Access to updated materials is available through your online account.
After purchase, you will receive your username and password immediately, allowing you to log in and download your study files without delay. Our goal is to support exam preparation at your pace with practice content designed for reinforcement and understanding of key concepts.
Killexams.com CGFM questions and answers cover all three exams with explanations.
Questions in the killexams.com CGFM bank are grouped to match the exam sections, including Governmental Environment; Accounting, Financial Reporting and Budgeting; and Financial Management and Control. Explanations accompany every answer, and repeated timed sessions build the speed and confidence needed on exam day.
Candidates who use the killexams.com CGFM question bank often begin with a diagnostic session to see which sections need the most attention, then return to those sections repeatedly before taking a final full length practice test.
Killexams.com keeps the CGFM question bank current by reviewing it when the exam outline changes, and each question includes an explanation so you learn the reasoning, not just the answer. The practice test can be repeated with questions in a different order, which helps you focus on understanding rather than memorizing positions.
Online Test Engine
| Exam Questions | 1103 (Complete Set) |
| Testing Limit | Unlimited |
| Access Type | Online |
| Latest Update | November 19, 2026 |
| Access Activation | Instant (5 to 10 min.) |
| Supported OS | Mac, Windows, Android, iPhone / iPad, Linux |
| Delivery Method | Username / Password |
Killexams.com provides an Online Test Engine designed to help candidates practice exam questions in a structured and interactive environment. The Test Engine is compatible with iPhone, iPad, Android, Windows, and Mac, allowing you to study and practice on the device that best fits your schedule.
The CGFM Online Test Engine enables candidates to simulate exam-style practice sessions, review answers, and track progress over time. This learning approach helps users practice exam questions, question formats and improve time management while preparing for the Certified Government Financial Manager exam.
The Test Engine includes features that support effective learning, such as customizable practice sessions, question review modes, and progress tracking. These tools are designed to assist candidates in identifying knowledge gaps and reinforcing key concepts through repeated practice rather than memorization alone.
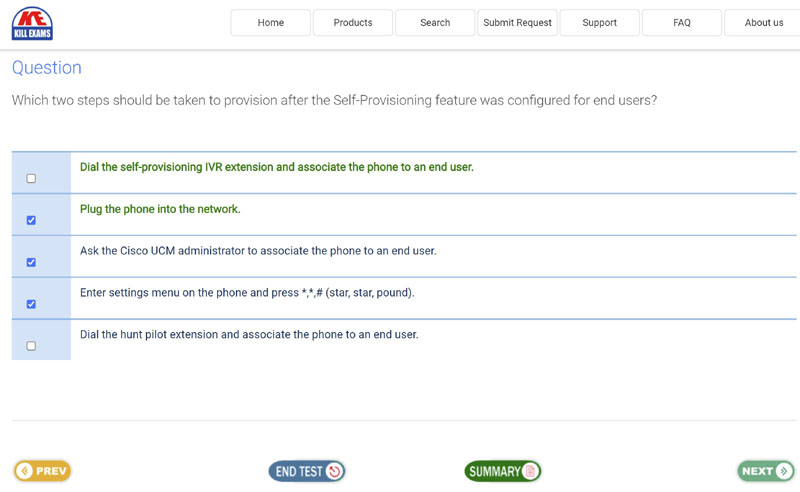
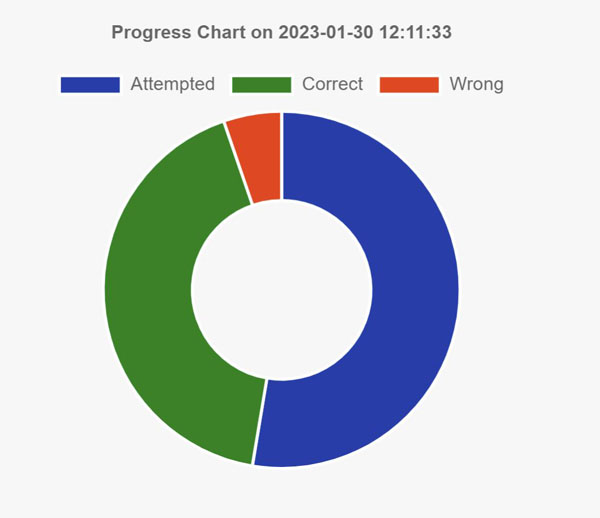
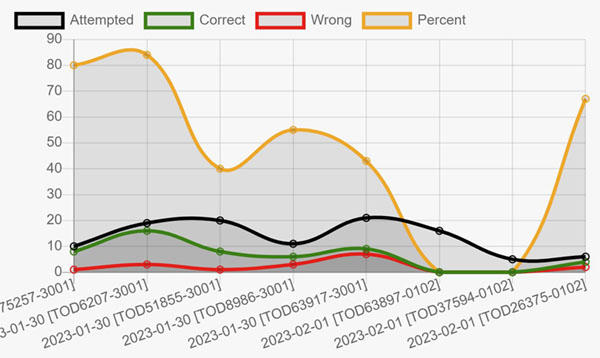
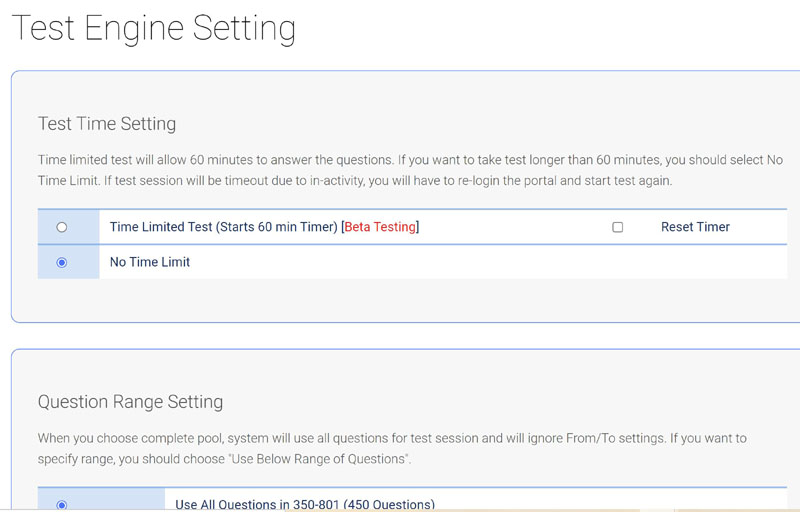
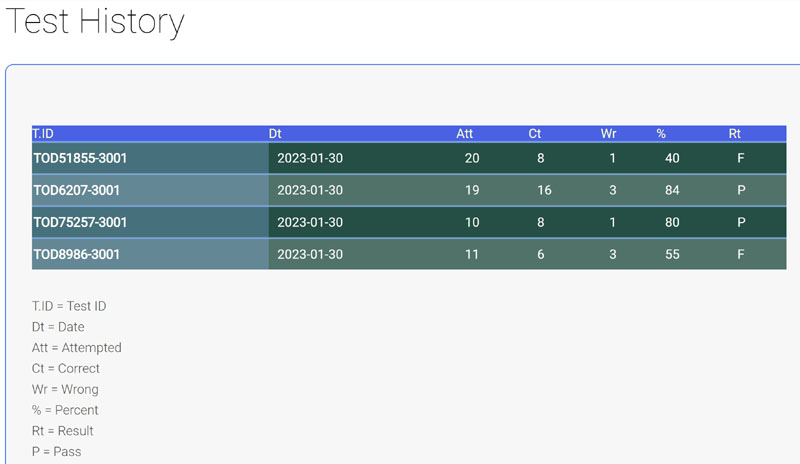
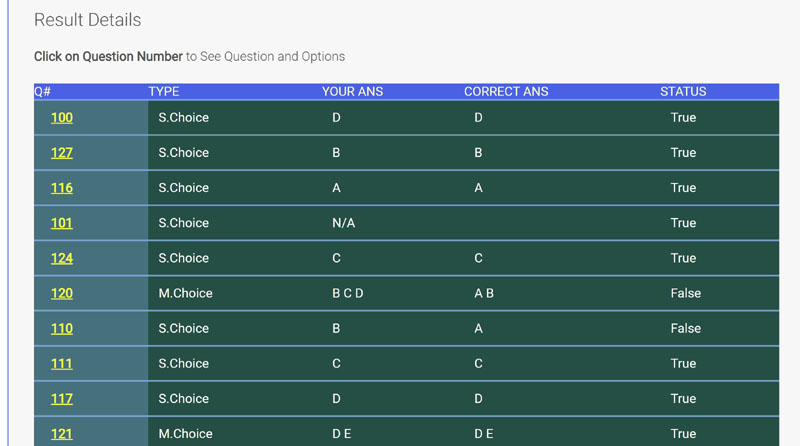
The Online Test Engine maintains practice history, performance summaries, and visual progress reports. Where available, questions may include explanations or reference information to support better understanding of exam topics. Content is reviewed and updated periodically to reflect relevant syllabus changes and maintain consistency with exam objectives.
Desktop Test Engine
| Exam Questions | 1103 (Complete Set) |
| Software Version | 2026 |
| Access | Unlimited |
| Latest Update | November 19, 2026 |
| Access Activation | Instant (5 to 10 min.) |
| Supported OS | Windows (All Versions) |
| Delivery Method | Username / Password |
| Test Engine Trial Software | Killexams Test Engine 2026 |
The Killexams Desktop Test Engine (version 2026) is a dedicated test preparation software designed to support candidates preparing for the CGFM exam. The simulator provides a structured desktop based practice environment that allows users to work through exam style questions and review their performance in detail.
By practicing with the Certified Government Financial Manager Exam Simulator, candidates can become familiar with question formats, exam navigation, and time based testing conditions similar to those used in official exams. This experience helps users build confidence across testing environment, time management, exam topics and identify areas that may require additional study.
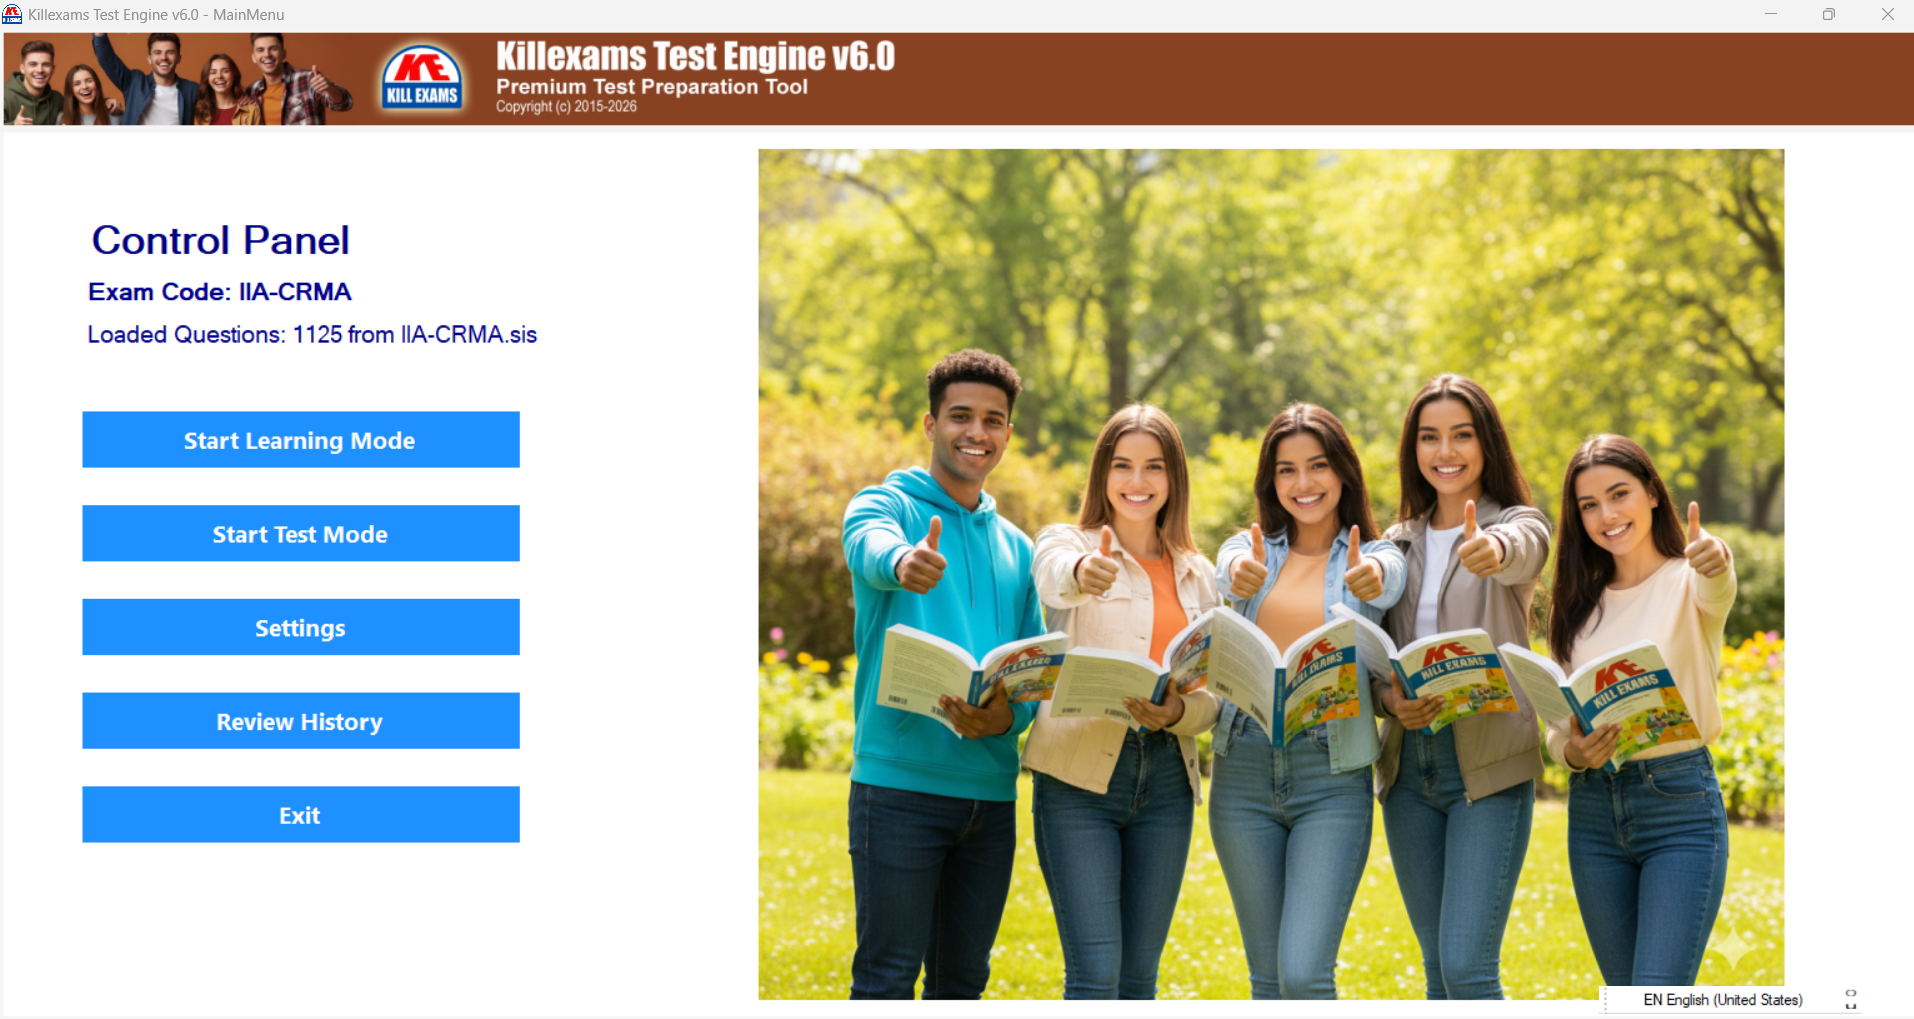
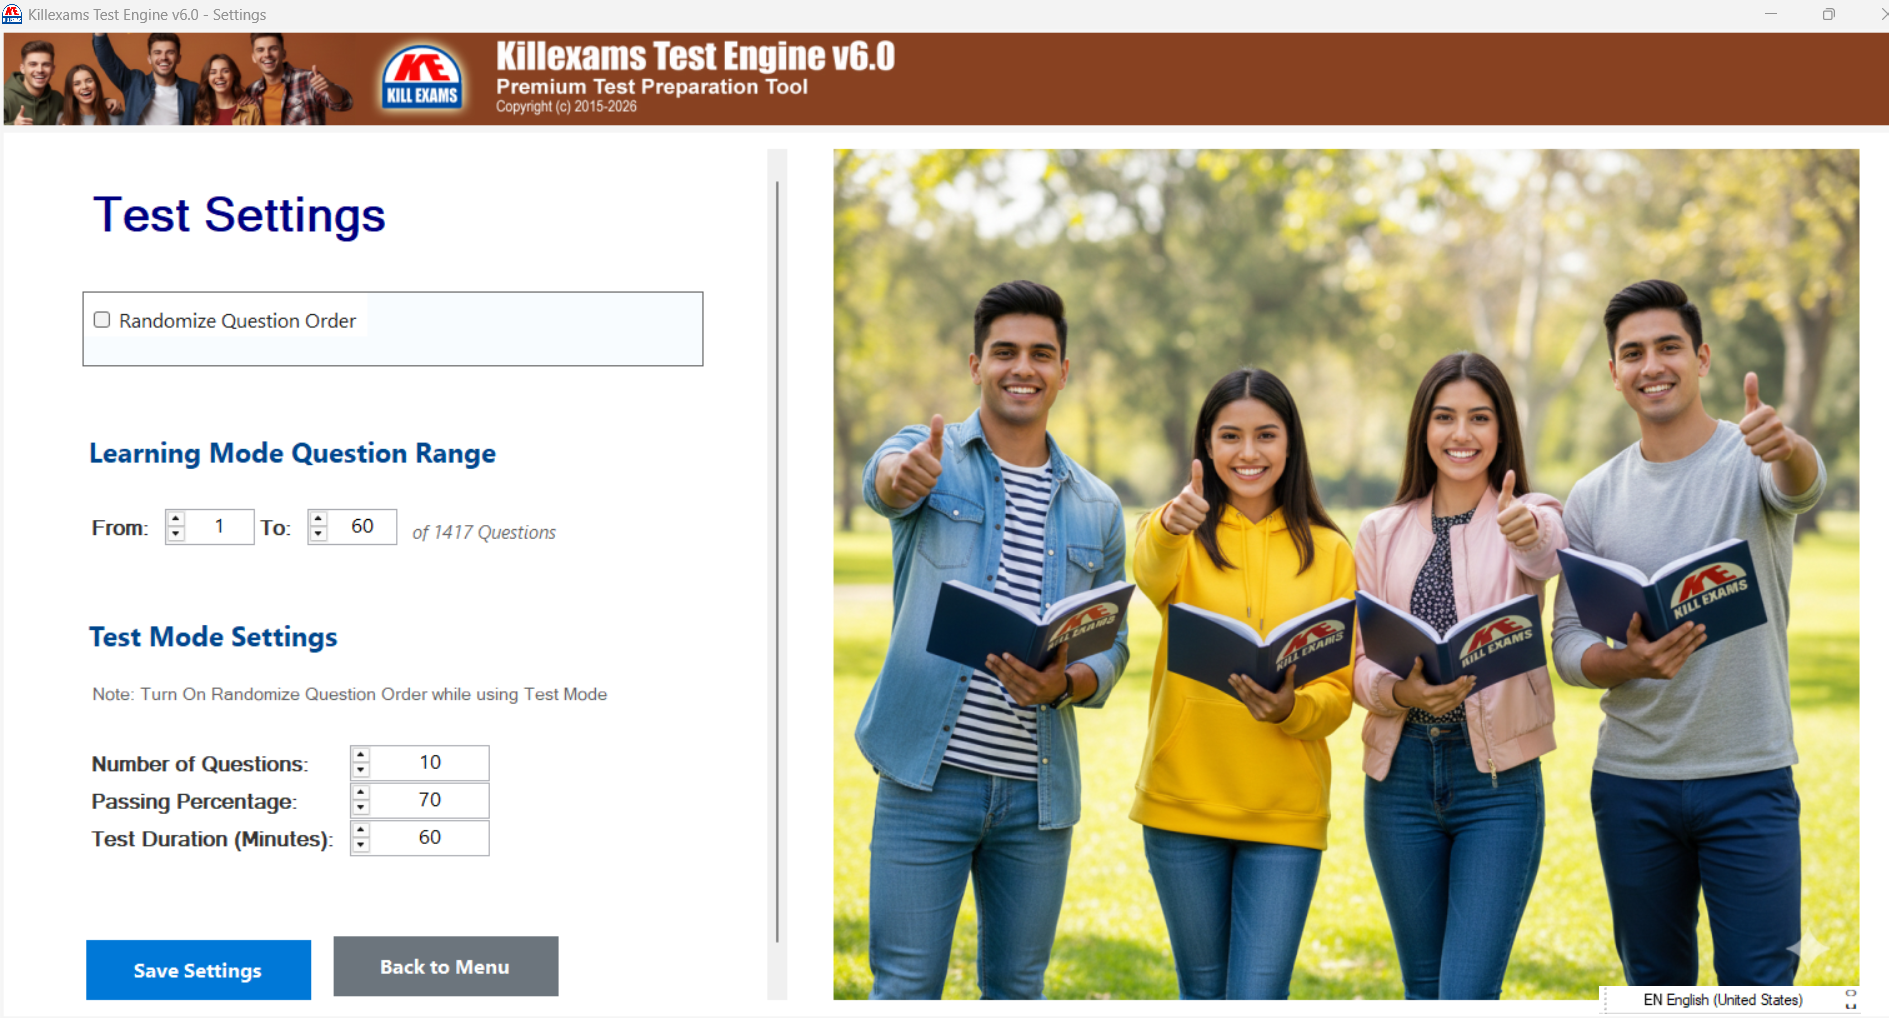
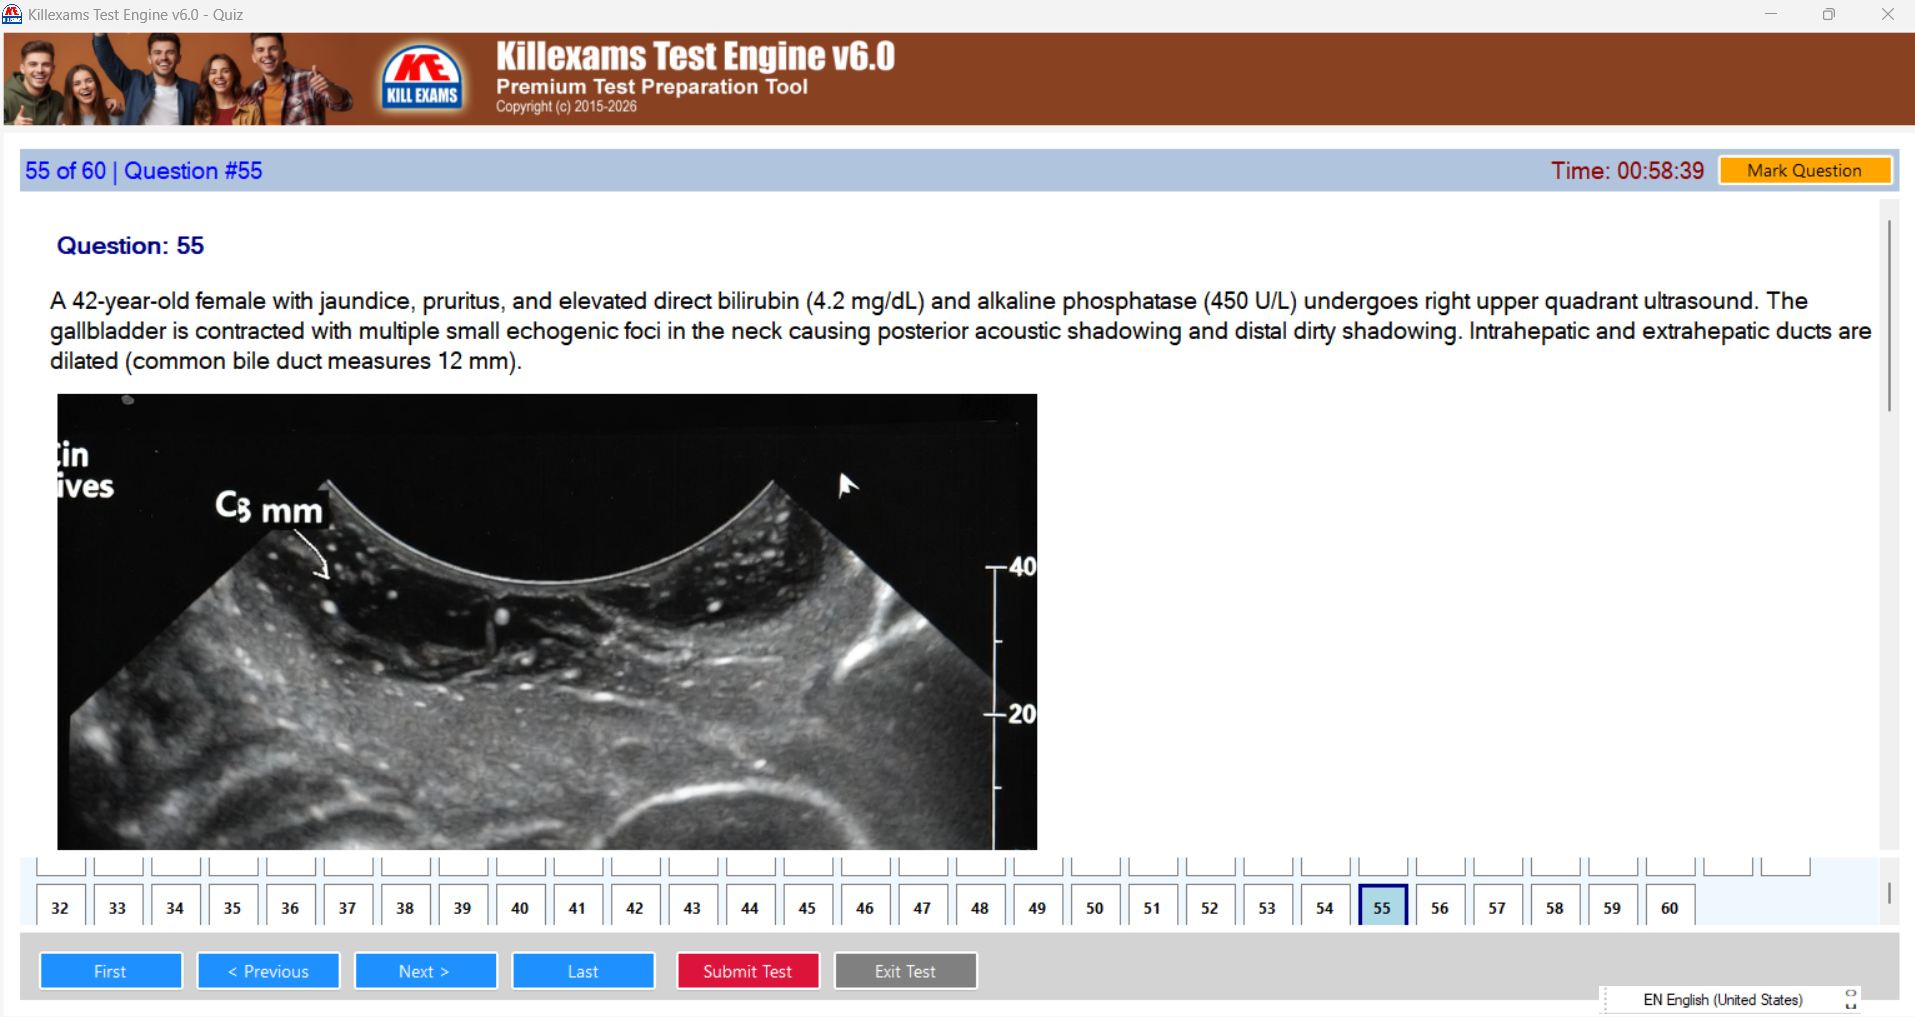
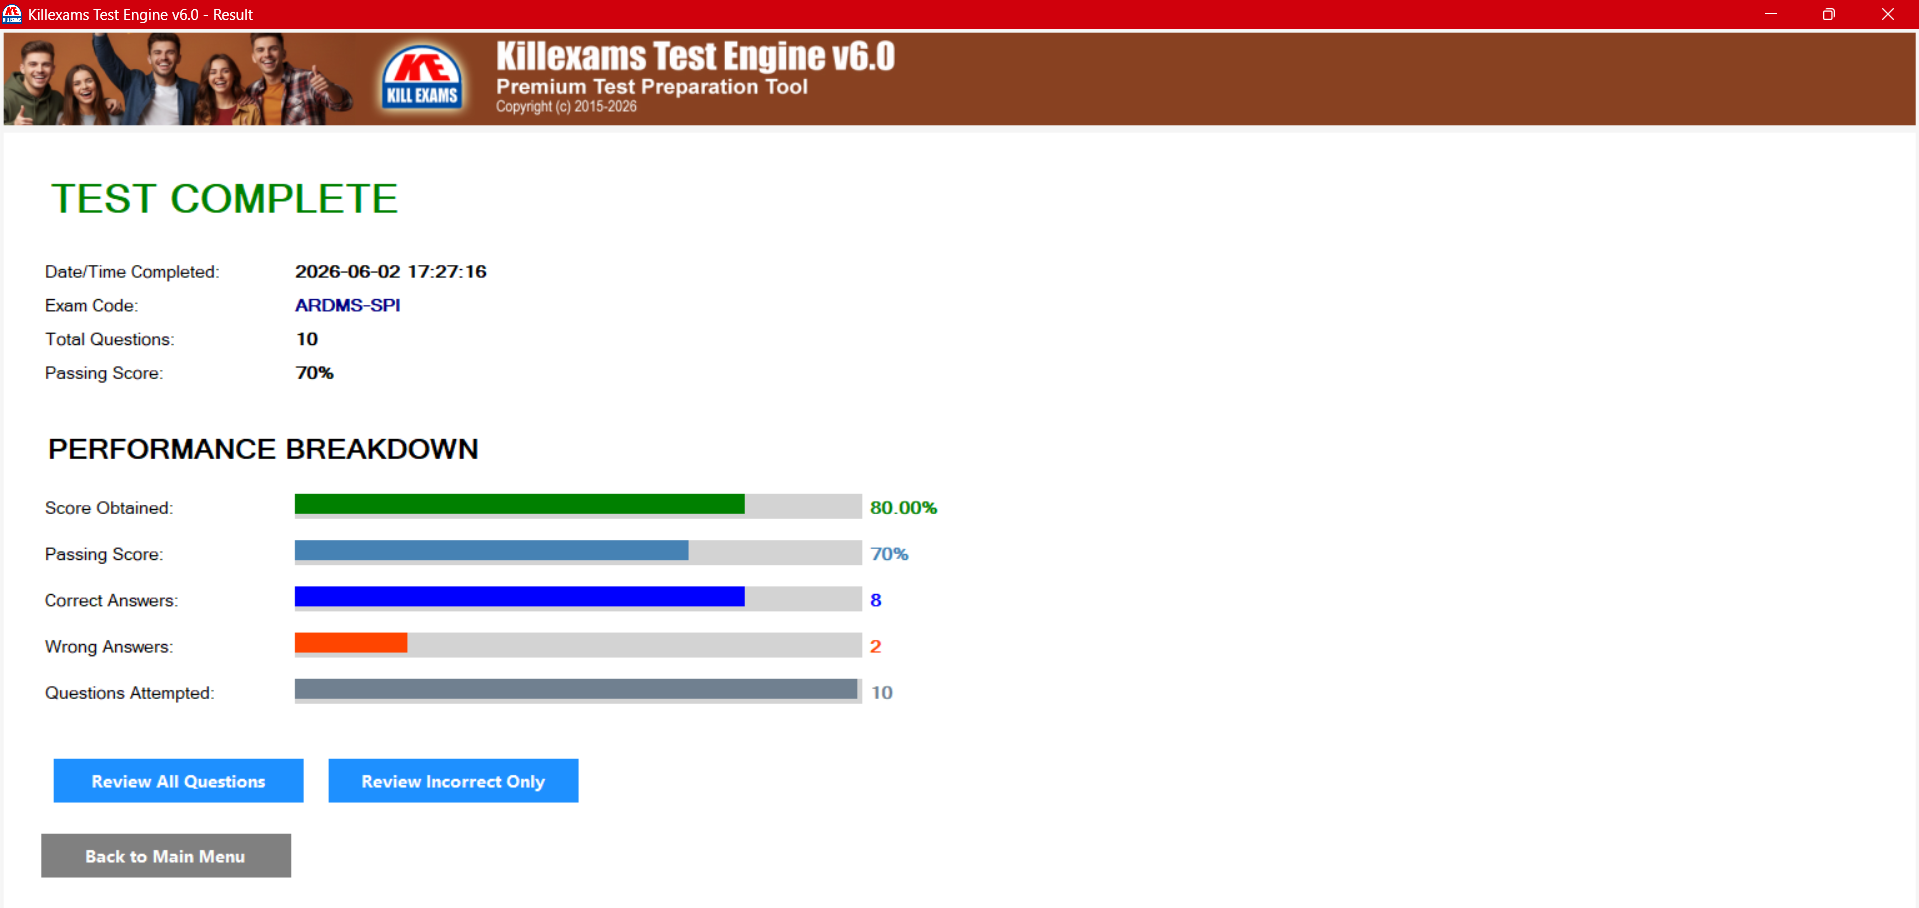

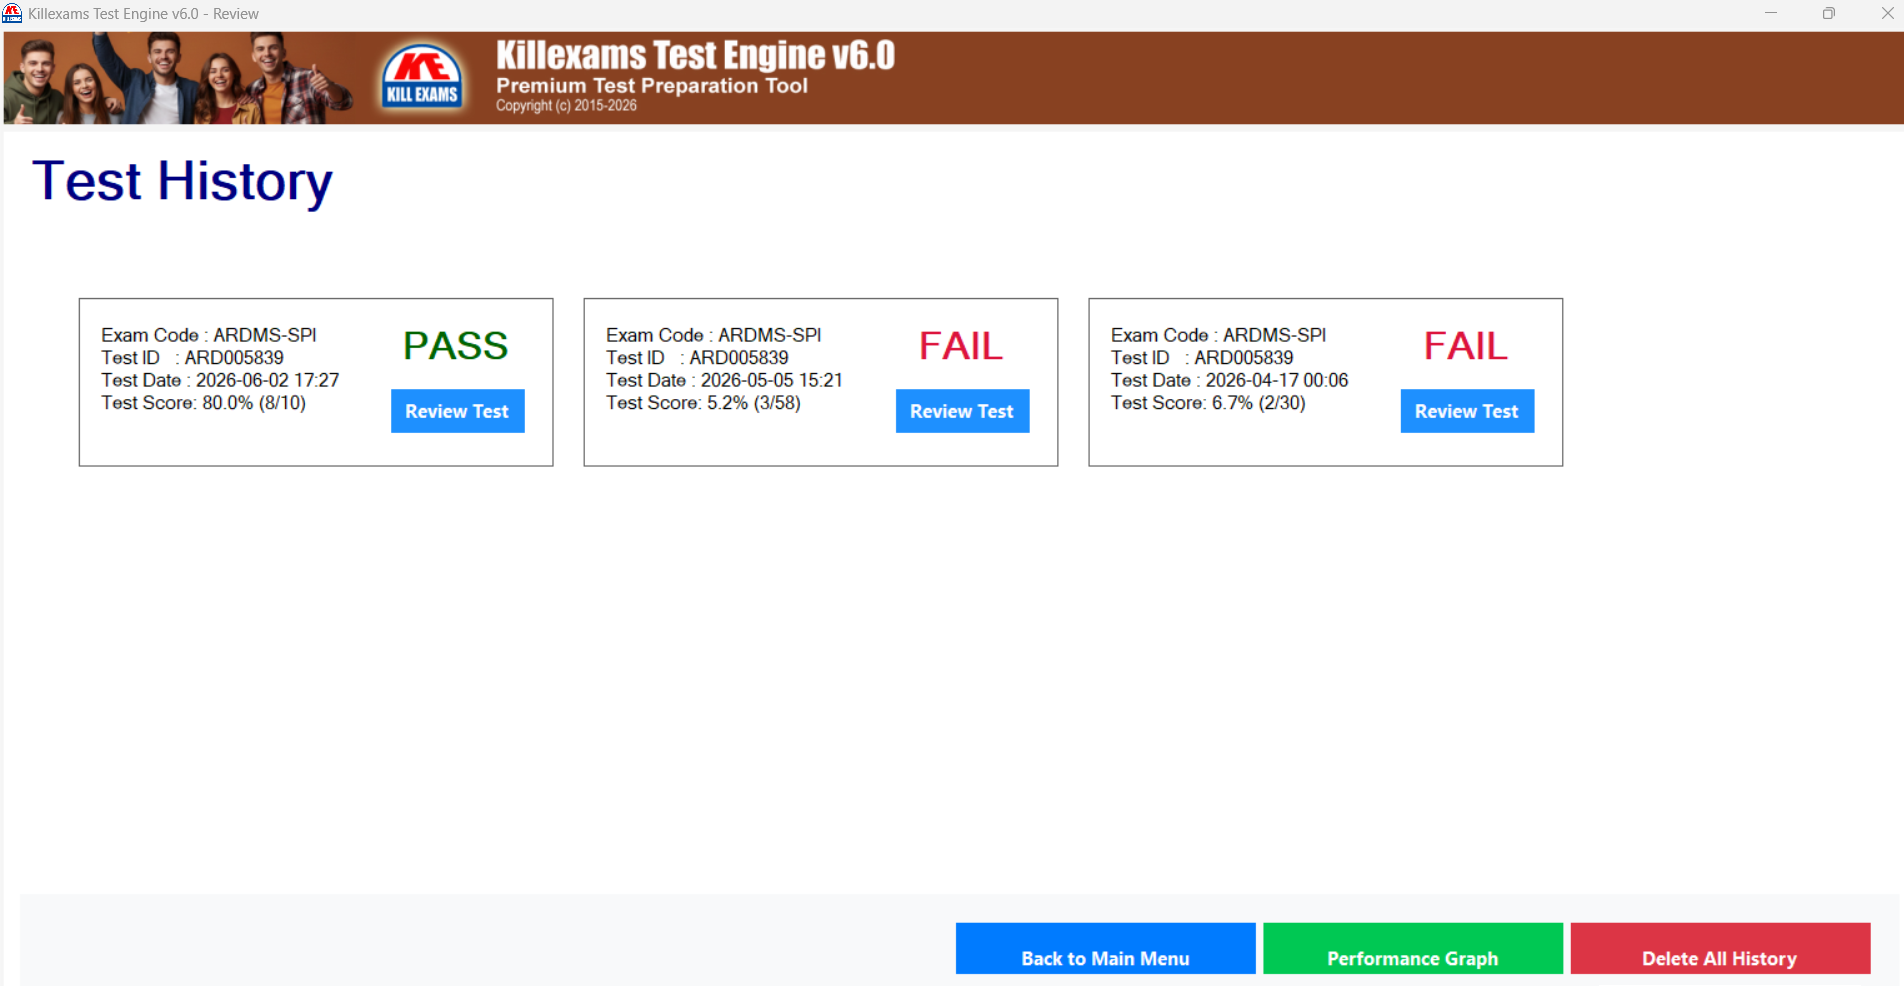
The Desktop Exam Simulator records practice history, performance summaries, and graphical progress reports. Where available, questions may include explanations or reference information to support understanding of correct and incorrect answers. The simulator content is reviewed and updated periodically to remain aligned with current exam objectives and syllabus requirements.
|
3 Months Update
|
6 Months Update
|
12 Months Update
|
|
|---|---|---|---|
What is 3 Months Update?
During 3 months, all future updates in PDF and Test Engine will be provided in your MyAccount with download links. An Intimation email on each update will be sent to you to re-download the updated exam files.
|
What is 6 Months Update?
During 6 months, all future updates in PDF and Test Engine will be provided in your MyAccount with download links. An Intimation email on each update will be sent to you to re-download the updated exam files.
|
What is 12 Months Update?
During 12 months, all future updates in PDF and Test Engine will be provided in your MyAccount with download links. An Intimation email on each update will be sent to you to re-download the updated exam files.
|
|
| Files | PDF / Test Engines | PDF / Test Engines | PDF / Test Engines |
| Premium Access | ✔ | ✔ | ✔ |
| Online Test Engine | ✔ | ✔ | ✔ |
| Instant Download Access | ✔ | ✔ | ✔ |
| Comprehensive Q&A | ✔ | ✔ | ✔ |
| Latest Topics | ✔ | ✔ | ✔ |
| Updated Regularly | ✔ | ✔ | ✔ |
| Portable Files | ✔ | ✔ | ✔ |
| Unlimited Download | ✔ | ✔ | ✔ |
| 100% Secured | ✔ | ✔ | ✔ |
| Confidentiality | 100% | 100% | 100% |
| Syllabus Coverage | Latest | Latest | Latest |
| Any Hidden Cost | No | No | No |
| Auto Renewal | No | No | No |
| Updates Intimation | by Email | by Email | by Email |
| Technical Support | Free | Free | Free |
| PDF Compatibility | Windows, Mac, Android, iOS, Linux | Windows, Mac, Android, iOS, Linux | Windows, Mac, Android, iOS, Linux |
| Desktop Test Engine Compatibility | Windows All Versions | Windows All Versions | Windows All Versions |
| Online Test Engine Compatibility | Mac / Windows / Android / iOS / Linux | Mac / Windows / Android / iOS / Linux | Mac / Windows / Android / iOS / Linux |
CGFM Exam Format | Course Contents | Course Outline | Exam Syllabus | Exam Objectives
Exam Name : Certified Government Financial Manager(R)
Questions : 115 questions
Duration : 2 hrs 15 min.
I: Organization- Structure and Authority of Government (15%)
A. Demonstrate an understanding of the levels of government- including:
- The three levels of government: federal- state and local.
- The interrelationships among the three levels of government: federal- state and local.
B. Demonstrate an understanding of the branches of government – legislative- executive- judicial – including:
- The roles of the three branches.
- The interrelationships among the three branches.
- The checks and balances through separation of powers among the three branches.
C. Demonstrate an understanding of the components of federal- state and local governments (e.g.- central management and accountability agencies- departments- agencies- bureaus- commissions- divisions).
D. Demonstrate an understanding of the authorities and responsibilities of the government (e.g.- government-wide and departmental)- including:
The federal government- its hierarchy and constraints (e.g.- U.S. Constitution- federal laws- executive orders- rules and regulations).
The state governments- their hierarchies and constraints (e.g.- U.S. Constitution- state constitutions- state laws- executive orders- rules and regulations).
The local governments- their hierarchies and constraints (e.g.- state constitutions- state laws- local charters- local ordinances- executive orders- rules and regulations).
Tribal government sovereignty.
E. Demonstrate an understanding of the authorities and responsibilities of the different types of governments- including:
The differentiation among general-purpose governments- special-purpose governments and quasi-governmental entities (e.g.- federal- states- cities- counties- territories- authorities- school districts- government corporations- government-sponsored enterprises).
The interrelationships among general-purpose governments- special-purpose governments and quasi-governmental entities.
The role of jointly-governed organizations (e.g.- transit agencies).
II: Legally-Based Implications of the Government Financial Environment (15%)
A. Demonstrate an understanding of the implications of sovereignty in the levels of government- including:
- The meaning- application and limitations of sovereign authority.
- The power of governments to tax and borrow.
- The power of the federal government to establish monetary policy.
B. Demonstrate an understanding of the budget- including:
- The role and significance of the budget in government.
- The objectives of the budget (e.g.- policy document- operations guide- financial plan- communications device).
- The objectives of the budget process (e.g.- define priorities- debate policy- allocate resources- identify revenue sources).
- The legal aspects of the government budget (e.g.- control levels- spending limits- fund types- balanced budgeting).
- The principles of legislative control over governmental finance (e.g.- appropriating funds- establishing spending levels- establishing spending conditions).
- How the executive branch controls spending (e.g.- monitoring budget execution- planning for allocation of resources over time and among programs).
- How judicial decisions affect government spending.
- The role of other budget control devices (e.g.- apportionments- allotments- encumbrances/obligations- funds- function- department- activity- object).
C. Demonstrate an understanding of how establishing special funds or dedicated revenues helps fulfill legal requirements.
D. Demonstrate an understanding of legislative “earmarking.”
III: Demonstrate an Understanding of the Government Management System (Cycle)- Including: (16%)
A. The elements of the government management system- including strategic planning- programming- budgeting- operations- accounting- reporting and auditing.
B. The interrelationships among the elements of the government management system.
C. The importance of data in the government management system (cycle).
IV: Governmental Financing Process (24%)
A. Demonstrate an understanding of the role of taxation- including:
- The elements of tax policy (e.g.- what to tax- who to tax- how much to tax- why to tax).
- The various types of taxes for each level of government and the roles and advantages of each type (e.g.- income- wealth- consumption).
- The nature and role of tax expenditures.
- Tax limitations and exclusions.
B. Demonstrate an understanding of intergovernmental revenues- including:
- The differences among contracts- shared revenues and grants.
- The differences among the types of grants (e.g.- formula grants- discretionary grants- block grants).
- The requirements and expectations of the grantor and grantee throughout the grant lifecycle- including the role of the Uniform Guidance.
C. Demonstrate an understanding of other forms of financing- including:
Other forms of government revenues (e.g.- investment income- user fees- licenses- lotteries- donations).
The rationales for establishing user fees (e.g.- recover costs- expand service capacity- encourage or limit use of services). The use of public-private partnerships.
D. Demonstrate an understanding of the role of debt- including:
- Purposes of entering into debt.
- Factors that should be considered before entering into debt (e.g.- ability to pay- purpose- interest rate- tax base).
- The types of debt limitations (e.g.- statutory- bond covenants).
- Factors that should be included in debt policies (e.g.- available tax base- debt maturities).
- The various types of financing options (e.g.- notes- bonds- lease-purchase- certificates of participation).
- The sources and methods of repaying debt (e.g.- dedicated taxes- user fees- general revenues).
- The role of credit rating agencies in the debt issuance process.
- The role of insurance and guarantees in the debt issuance process.
V: Identify the Concepts- Definitions and Notions of Public Accountability- Including: (12%)
A. The meaning and purpose of accountability in the government environment (e.g.- the Chief Financial Officers (CFO) Act of 1990).
B. The role and key attributes of accountability (e.g.- disclosure- organization structure- reporting)- and their interrelationships.
C. Elements for which a government should be accountable (e.g.- performance- financial- compliance- efficiency and effectiveness- stewardship of assets).
D. The primary stakeholders in accountability (e.g.- legislators- taxpayers- other governments- investors- creditors- underwriters- future generations).
E. The groups that help to establish and maintain accountability (e.g.- legislative bodies- media- management- analysts- employees- taxpayers).
F. The methods used to demonstrate and assess accountability and transparency (e.g.- audit reports- performance reports- oversight hearings- program evaluations- service efforts and accomplishment (SEA) reports- electronic reports).
G. The techniques used to assess fiscal sustainability and solvency.
H. Concepts of open government- data transparency and citizen-centric reporting (e.g.- Digital Accountability and Transparency Act of 2014 (DATA Act)- open checkbooks- open book- sunshine laws).
VI: Demonstrate an Understanding of Ethics as Applied to the Government Environment- Including: (10%)
A. The key concepts related to ethical responsibility to the public- professional conduct (e.g.- actual or perceived conflicts of interest- independence- objectivity- due care) and the sources of guidance (e.g.- the AGA Code of Ethics).
B. The steps a government financial manager needs to take to avoid a conflict of interest and to ensure objectivity and independence.
C. The concept of due care in the performance of professional duties.
D. Activities or situations that are inconsistent with the responsibilities of public officials and employees.
E. The appropriate course of action to avoid the reality or the perception of improper use of one's office for personal gain.
F. Personal responsibility as it relates to organizational codes of conduct (e.g.- whistle blower- nepotism).
VII: Demonstrate an Understanding of Providing Government Services and Information Electronically- Including: (8%) A. Delivery of government services and e-government (e.g.- drivers license renewal- online bill and tax payment).
B. Stakeholder real-time access to information- including electronic financial reporting.
C. The use of various media and devices for communications and providing services (e.g.- social networking- apps- mobile devices).
D. Security and privacy considerations (e.g.- the requirements of the National Institute of Standards and Technology- encryption- cybersecurity).
I: Governmental Financial Accounting- Reporting and Budgeting: General Knowledge (40%)
A. Demonstrate an understanding of the influences- objectives and role of standards- including:
The unique financial aspects of the governmental environment that differ from the private sector (e.g.- profit versus service- importance of budget).
The concept of interperiod equity.
The objectives of governmental financial reporting (e.g.- financial accountability- budgetary accountability- program accountability).
The major uses of governmental financial reporting (e.g.- budgetary compliance- compliance with laws and regulations- assessing financial position- assessing results of operations- assessing sustainability).
The characteristics of information in governmental financial reporting (e.g.- understandability- reliability- relevance- timeliness- consistency- comparability).
The roles of the Financial Accounting Standards Board (FASB)- Governmental Accounting Standards Board (GASB) and Federal Accounting Standards Advisory Board (FASAB).
The role of the International Public Sector Accounting Standards Board (IPSASB).
Due process in the setting of accounting standards (e.g.- discussion memorandum- invitation to comment- preliminary views- exposure draft- public hearing- task forces).
The purpose of the hierarchy of generally accepted accounting principles for state/local and federal accounting and financial reporting.
The basic concepts and requirements of Open Government financial reporting.
B. Demonstrate an understanding of the concepts of managerial cost accounting and fee establishment- including:
The purposes for accumulating and reporting cost information.
The concept of full cost of outputs- incorporating inter-entity costs.
The requirements of FASAB Statement of Federal Financial Accounting Standards (SFFAS) 4- as amended: Managerial Cost Accounting Concepts and Standards.
Determining the costs under an intergovernmental cost-reimbursement contract or grant (as outlined in the Uniform Guidance).
Identification of the methods for assigning and allocating costs in a given situation (e.g.- direct- indirect).
Computation of the fee to be charged to a user.
Various cost recovery objectives (e.g.- total direct costs- operating costs- full costs- replacement costs- incremental costs).
C. Demonstrate an understanding of the concepts of budgeting- including:
The key elements of the budget process- from provision of initial guidance through preparation- review- adoption- execution and accounting.
The structure of the budget (e.g.- organizational unit- program- function- category- character- fund- line item- object).
The features of various budgetary approaches (e.g.- baseline- line item- program- zero-base- performance).
The various means for financing capital projects- including the role of a capital budget.
The methods of forecasting revenues and expenditures.
The various means of budgetary control (e.g.- revenue monitoring- encumbrance/obligation control- vacancy controls- allotment- apportionment).
D. Demonstrate an understanding of the general principles of governmental financial accounting- including:
Basic accounting processes (e.g.- debits- credits- ledger accounts- stock and flow statements- accounting period).
The differences among the various measurement focuses and bases of accounting (e.g.- economic resources- current financial resources- cash- accrual- modified accrual).
The effect of applying the various measurement focuses and bases of accounting to specific transactions.
Exchange and exchange-like versus non-exchange transactions.
How to adjust the allowance for doubtful accounts under alternative methods (e.g.- percentage of sales or percentage of accounts receivable).
The differences among various methods of valuing inventory (e.g.- First-in- First-out (FIFO)- Last-in- First-out (LIFO)- average cost).
Situations that require recording depreciation and calculation of the same.
Recording contingencies (e.g.- judgments- claims).
II: Demonstrate an Understanding of State and Local Financial Accounting and Reporting- Including: (30%)
A. The application of the GASB standards for determining the reporting entity- including component units.
B. The purpose of each fund type within each fund category- and its related basis of accounting.
C. The form and content of the Comprehensive Annual Financial Report (CAFR).
D. The purpose of popular reporting.
E. The form and content of the basic financial statements- including:
Government-wide financial statements.
Fund-level financial statements.
Notes.
F. The reporting of fund balance in governmental funds.
G. The form and purpose of required supplementary information (RSI).
H. How to measure- record and report the purchase of capital assets- including assets acquired through a capital lease.
I. How to measure- record and report the incurrence and repayment of general long-term obligations in a governmental fund.
J. How to measure- record and report common- fundamental current assets and liabilities- revenue- expenditures- and other financing sources and uses when using modified accrual basis of accounting (e.g.- property tax- grants- shared revenues- capital outlays- bond proceeds- debt service- payroll- accounts receivable).
K. How to measure- record and report common- fundamental assets- liabilities- revenue and expense transactions when using accrual basis of accounting (e.g.- taxes- grants- shared revenues- capital assets- long-term debt- operating expenses- pensions- payroll- accounts receivable).
L. The types of interfund transactions- and how they are accounted for.
M. How to consolidate or eliminate transactions between the fund level and the government-wide level for governmental activities.
N. The required disclosures for cash deposits with financial institutions and investments- including repurchase agreements.
O. The option and criteria for using the modified approach for infrastructure.
P. The entries for recording the budget- modifying the budget and recording encumbrances and expenditures.
Q. How to reconcile the budgetary information to the generally accepted accounting principles (GAAP) information.
R. How to reconcile the fund financial statements to the government-wide financial statements.
S. Government combinations (e.g.- mergers and acquisitions- transfers of operations).
III: Demonstrate an Understanding of Federal Financial Accounting and Reporting- Including: (30%)
A. The role of FASAB and the relationships among the Office of Management and Budget (OMB)- U.S. Department of the Treasury and the Government Accountability Office (GAO) in federal financial accounting and reporting.
B. Key budgetary terms (e.g.- appropriations- budget authority- budgetary resources- object class- outlays- receipts- offsetting collections- deficit).
C. The components of the budgetary equation.
D. The relationship and differences between budgetary and proprietary accounting.
E. Types of funds (e.g.- general- trust- revolving).
F. The components and use of the U.S. Standard General Ledger.
G. How to record common- fundamental budgetary transactions (e.g.- appropriation- apportionment- allotment- commitment- obligation- expenditure).
H. How to record common- fundamental proprietary transactions (e.g.- warrants- accounts payable- payroll- accounts receivable- pensions- investments- depreciation).
I. Determining the reporting entity.
J. The form and content of an agency financial report (AFR) and a performance and accountability report (PAR).
K. The purposes- form and content of the basic financial statements.
L. The concepts of consolidation and intragovernmental transactions.
M. The purposes and form of the notes to the financial statements.
N. The purposes and form of required supplementary information (RSI).
O. The concept of Fund Balance with Treasury.
P. The concepts of accounting for loans and loan guarantees (Credit Reform Act).
Q. The basic requirements for the U.S. Consolidated Financial Report.
I: Financial Management Functions (25%)
A. Demonstrate an understanding of cash management- including:
Legislation that affects governmental cash management.
Controls appropriate for governmental cash management.
Considerations in establishing banking relationships (e.g.- competition- servicing- compensating balance).
Techniques for accelerating collections (e.g.- electronic fund transfer (EFT)- centralized collections- lockboxes- e-Collections).
Techniques for timely payment (e.g.- warehousing payments- EFT- credit cards- electronic invoicing).
The role and control of electronic payments (e.g.- smart cards- benefit cards- EFT).
The existence of and the need to identify- prevent and recover improper payments.
B. Demonstrate an understanding of investment management- including:
Concepts and relationships among risk- liquidity and yield- and the associated tradeoffs.
Types of investments for operating funds and pensions.
The concept of fiduciary responsibility- including the duty of loyalty and duties to care- act in a prudent manner and diversify plan assets.
The components of an investment policy- including standards of care- objectives- conflicts of interest and authorization.
Investment management considerations (e.g.- selection of money managers- role of prudent experts- understanding of markets- monitoring and evaluating performance- risk assessment/avoidance- internal controls).
C. Demonstrate an understanding of loan and loan guarantee programs and debt collection- including:
The components of loan and loan guarantee programs (e.g.- rationale- credit extension- account servicing- debt write-off- performance measurement).
The components of delinquent debt collection (e.g.- salary and refund offsets- collection agencies- delinquency rates- aging- reporting requirements).
D. Demonstrate an understanding of procurement management- including:
The elements in the public procurement process (e.g.- authorized procurement officials- compiling a bidders list- public advertising- preparing and issuing an invitation to bid (ITB) or a request for proposal (RFP)- evaluating proposals- awarding the contract- writing the contract).
Techniques for assuring full and fair competition (e.g.- advertising- direct contact to likely vendors- registries).
Contract efficiencies (e.g.- purchase cards- bulk purchasing- inter-agency procurements).
Evaluation selection criteria (e.g.- past performance- delivery time- price).
The monitoring and acceptance process to ensure that contract specifications are met.
E. Demonstrate an understanding of property management- including:
The elements of a property management system (e.g.- record keeping- safeguarding- maintenance- reporting).
The procedures for property disposal (e.g.- identifying surplus- disposition methods).
F. Demonstrate an understanding of operating materials and supplies/inventory management- including:
The elements of an operating materials and supplies/inventory management system (e.g.- policies- classifications- controls- reorder decisions).
Ways to safeguard operating materials and supplies/inventory (e.g.- physical control- tagging- periodic inventory- stewardship- radio-frequency identification (RFID).
G. Demonstrate an understanding of financial management systems- including:
The concept of an integrated financial management system.
User needs for real-time access to data across the enterprise (e.g.- use of dashboards- data visualization).
Business process re-engineering in the development and implementation of information systems.
The concept of enterprise resource planning (ERP) systems.
The various approaches to meeting system needs (e.g.- off-the-shelf- cross-servicing- outsourcing- custom design- shared services).
The elements of a disciplined development process (e.g.- requirements management- testing- data conversion- systems interfaces- configuration management- risk management- project management- quality assurance).
Techniques for project management (e.g.- defining interrelationships and tasks; resource management; cost- schedule and performance monitoring; independent verification and validation; change management).
Methods for assuring the reliability and completeness of data.
The concept of the continuity of operations plan (COOP).
The use of cloud computing.
H. Demonstrate an understanding of shared services- including:
The service offerings- planning- transition steps and costs of shared support services.
Importance- advantages and disadvantages of shared services.
II: Demonstrate an Understanding of Financial and Managerial Analysis Techniques- Including: (15%)
A. The conduct of the following types of analyses: present value- future value- cash flow- pay-back- trend- ratio analysis- strategic sourcing- regression analysis- earned value management and flowcharting.
B. Identification of the sources of information used and reliability of the data for financial and managerial analysis (e.g.- accounting records- performance records- financial statements- census data).
C. The use of forensic techniques- such as data mining.
D. The use of advanced data analytics.
III: Internal Control (25%)
A. Demonstrate an understanding of internal control- including:
The objectives of internal control.
The concepts of cost-benefit and reasonable assurance.
The components and principles of internal control- as specified by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) Integrated Framework: control environment- risk assessment- control activities- information and communication- and monitoring.
Cyber security (e.g.- general and application controls).
Identification and correction of internal control deficiencies.
Involvement of shared service providers.
B. Demonstrate an understanding of the application of internal control to:
Programs and operations- including information technology.
Financial reporting.
Compliance.
Fraud- waste and abuse prevention and detection.
C. Demonstrate an understanding of internal control responsibilities- including:
Management's responsibility to establish- monitor- remediate and report on internal control.
Management's responsibility for detecting and reporting fraud- waste and abuse.
The independent auditor's responsibility regarding internal control.
The roles of the internal auditor in the internal control process.
D. Demonstrate an understanding of the internal control evaluation process- including:
The process for documenting and assessing internal control.
The roles of management and the auditor in the evaluations of internal control including the risk of fraud- waste and abuse.
E. Demonstrate an understanding of the internal control reporting process- including:
How management reports on internal control- including the use of various types of assertions.
The auditor's reporting on internal control.
F. Demonstrate an understanding of Enterprise Risk Management (ERM)- including:
Relationship to internal control.
Application of ERM.
IV: Demonstrate an Understanding of Performance Measurement/Metrics/Service Efforts and Accomplishments (SEA)- Including: (15%) A. The objectives of financial and non-financial performance measures.
B. How performance measures relate to organizational goals and objectives.
C. How financial and non-financial performance measures are linked.
D. How financial and non-financial performance measures are integrated with the strategic plan and budget.
E. The uses of performance measurement and reporting to demonstrate public accountability and transparency.
F. The uses of performance measurement and reporting to improve allocation of resources and oversight of performance.
G. The uses of performance measurement and reporting to improve effectiveness and efficiency.
H. The types of performance measures: inputs- outputs- outcomes and efficiency measures.
I. The characteristics of performance measurement data (e.g.- relevant- understandable- comparable- reliable- timely- verifiable- actionable- cost-beneficial).
J. Baselines and benchmarks.
K. The role of stakeholder input in the performance process.
L. The legal requirement and guidance for performance measurement.
V: Auditing (20%)
A. Demonstrate an understanding of auditing- including:
Types of auditors (e.g.- external- internal).
Objectives of financial audits.
Objectives of attestation engagements.
Objectives of performance audits.
Uses of audit reports.
The concept of materiality.
B. Demonstrate an understanding of standards- including:
The sources of auditing standards for audits of government organizations.
The interrelationships among various audit standards-setting organizations (e.g.- the Government Accountability Office (GAO)- American Institute of Certified Public Accountants (AICPA) Auditing Standards Board and the Public Company Accounting Oversight Board (PCAOB)).
The concept of general standards (e.g.- independence- professional judgement- competence- quality control and assurance).
The concept of auditor independence and the impact of non-audit professional services on independence.
Standards for financial audits.
Standards for attestation engagements.
The responsibilities of the auditor in an audit follow-up program.
Fieldwork and reporting standards for performance audits.
The types of activities that are considered sensitive in a government audit (e.g.- taxpayer information- payments to informants- the Health Insurance Portability and Accountability Act (HIPAA) data- personally identifiable information (PII)).
C. Demonstrate an understanding of the responsibilities of the auditee- including tasks related to:
Preparing for and procuring audit services.
Supporting the audit process.
Preparation of the management representation letter.
Audit follow-up and corrective action plan based on audit findings.
The role of an audit or audit advisory committee.
D. Demonstrate an understanding of the components of the Single Audit Act and the role of the Office of Management and Budget (OMB)- including:
The scope and purpose.
The required reports.
Reviews (2)3.00 Overall
★★★★★
0%
★★★★
50%
★★★
0%
★★
50%
★
0%
|
Submit ReviewYou must be logged in to submit a review. Sign In to Submit Review |
Customer Reviews
CGFM Exam FAQs
How many questions are on the CGFM exam?
The CGFM exam has 115 each questions.
How long is the CGFM exam?
You have 2 hrs 15 min to complete the CGFM exam.
What topics does the CGFM exam cover, and how are they weighted?
The CGFM exam covers 3 sections: Governmental Environment; Accounting, Financial Reporting and Budgeting; Financial Management and Control.
How should I prepare for CGFM?
Start with the official CGFM exam outline and study materials from AGA, then build exam readiness with timed practice. A killexams.com premium account gives you the full pool of 1,103 CGFM practice questions and answers in PDF and Test Engine formats, so you can practice every objective and review the answers before exam day.
How long does it take to prepare for CGFM?
At a steady pace of 100 practice questions a day, working through all 1,103 CGFM questions takes about 12 days. Add extra days to repeat the questions you got wrong.
Is CGFM hard? Who is it for?
The Certified Government Financial Manager credential from AGA recognizes financial professionals in government.
How many practice questions do you have for CGFM?
The killexams.com CGFM practice test contains 1,103 questions and answers.
Is there a free CGFM sample?
Yes. A free CGFM sample PDF is available on this page, so you can review the question style before you buy.
What formats are included in the CGFM practice test?
The CGFM practice test is available as a PDF, an Online Test Engine and a Desktop Test Engine.
Do the CGFM practice questions cover the current exam objectives?
Yes. The CGFM practice questions cover the complete syllabus and current exam objectives.
How do I get the files after purchase, and how long is access valid?
Your MyAccount login details are delivered by email. You can download the files from the member area until your account expires, after 3, 6 or 12 months depending on the plan you bought.
Can I use the CGFM Test Engine on Mac or mobile?
Yes, with the Online Test Engine, which runs on Mac, iOS, Android, Linux and other platforms. The Desktop Test Engine is for Windows only.
What if I fail the CGFM exam after using your material?
You can choose one of three options: 1) a refund, 2) a free 3-month account extension, or 3) a new exam of your choice.
How many practice questions are available for CGFM?
The CGFM practice test contains 1,103 practice questions and answers covering the current exam objectives.
What formats are available for CGFM preparation?
The CGFM practice test is available as PDF, Online Test Engine, Desktop Test Engine. All formats can be downloaded instantly after purchase.
Is there a free CGFM sample?
Yes. You can preview and download a free CGFM sample PDF on this page before you buy.